FICO Isn't the Only Game in Town Anymore
I saw the post pictured with this article and immediately wanted to know whether it was true.
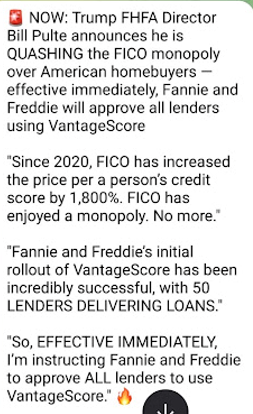
The claim was dramatic: the FICO “monopoly” was being quashed, Fannie Mae and Freddie Mac lenders could use VantageScore, and the mortgage credit-scoring world had suddenly changed.
So, I investigated.
Some of it is true. Some of it—not so much.
But underneath the exaggerated social-media wording is a genuine change that homebuyers should know about.
What Actually Changed?
For decades, mortgages delivered to Fannie Mae and Freddie Mac generally relied on versions of what is now called Classic FICO. That meant one scoring model held an extraordinarily important position in conventional mortgage lending.
That is changing.
On September 9, 2026, Fannie Mae and Freddie Mac expanded the availability of VantageScore 4.0 to all of their approved lenders. Prior written approval, which had been required during the limited rollout, is no longer necessary. “FHFA.gov”
That does not mean every mortgage lender in America was suddenly “approved” to use VantageScore, as the screenshot might lead someone to believe.
It means approved Fannie Mae and Freddie Mac lenders can now choose VantageScore 4.0 for eligible loans under the applicable requirements.
And it does not mean FICO is gone.
So, Did They Really End the “FICO Monopoly”?
Not exactly.
Classic FICO remains an approved option. For eligible loans sold to Fannie Mae and Freddie Mac, lenders currently may use Classic FICO or VantageScore 4.0. Fannie Mae also makes clear that adoption of VantageScore 4.0 is optional. FHFA.gov
There is another model coming into the picture as well: FICO Score 10T.
FICO 10T and VantageScore 4.0 were both approved by the Federal Housing Finance Agency in 2022 as part of a broader effort to modernize mortgage credit scoring and introduce competition into a system that had long depended upon Classic FICO. “FHFA.gov”
But FICO 10T is not yet available for loans delivered to Fannie Mae, and FHFA says it is not currently eligible for delivery to the Enterprises. Its implementation is still coming. “FHFA.gov”
Classic FICO is expected to be retired eventually, but as of now, no retirement date has been announced. “FHFA.gov”
So, the Facebook version — FICO is finished — makes a much better headline than it does a statement of fact.
The more accurate headline is:
FICO finally has competition.
Why Should a Homebuyer Care?
This is where the story becomes more interesting than the headline.
Newer credit-scoring models can consider information differently from the older Classic FICO models. FHFA specifically points to additional information such as rent-payment history, and the newer models also make use of more modern credit information and methodologies. “FHFA.gov”
That could matter particularly to someone who responsibly pays rent every month but has a thinner traditional credit history.
Think about that.
Someone may have paid $1,500, $2,000 or more in rent every month for years, yet historically that responsible payment history has not necessarily helped a mortgage credit score in the same way that paying a credit card or car loan has.
A scoring model capable of considering more of that financial behavior could potentially produce a different picture of that borrower.
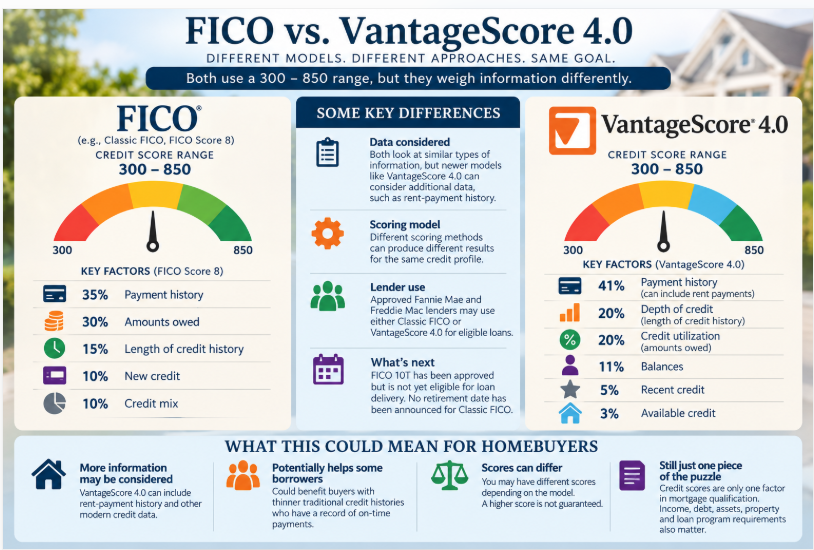
Different does not automatically mean better.
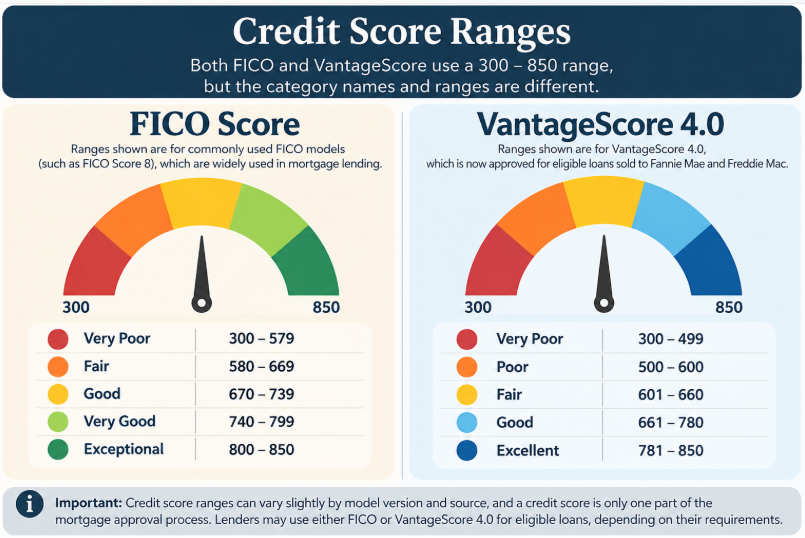
A VantageScore 4.0 score could be higher, lower or simply different from a Classic FICO score depending upon the borrower's credit profile. And a credit score remains only one part of mortgage qualification. Income, debt, employment, assets, property, loan program and underwriting requirements still matter.
But having another validated scoring model available means a borrower's mortgage prospects are no longer necessarily being viewed through only one scoring lens.
And Something Else Just Changed
There has already been another development since the September announcement.
On September 30, Fannie Mae and Freddie Mac announced changes aligning certain upfront credit-related pricing across Classic FICO and VantageScore 4.0. Fannie Mae says its updated loan-level price adjustments apply beginning October 1. “FHFA.gov”
In other words, this isn't merely an announcement about something that might happen years from now.
The transition is already underway.
What Should Buyers Do?
Don't throw your FICO score out the window.
Don't assume VantageScore will qualify you for a mortgage when FICO won't.
And definitely don't assume that because an app or website shows you a particular VantageScore, that is automatically the score a mortgage lender will use.
Instead, if you are preparing to buy a home, this gives you one more good question to ask your lender: Which credit-scoring model will you be using for my loan?
If credit is one of the obstacles standing between you and homeownership, it may also be worth asking whether an eligible loan using VantageScore 4.0 could produce a different result in your particular situation.
The answer won't be the same for everybody.
The Bigger Picture
This is why I don't automatically share something simply because it appears in my social-media feed.
The screenshot that started this article wasn't completely wrong.
But it wasn't completely right either.
The “FICO monopoly” didn't disappear overnight. Classic FICO is still being used. VantageScore 4.0 is now broadly available to approved Fannie Mae and Freddie Mac lenders for eligible loans, and FICO 10T is still waiting in the wings. “FHFA.gov”
The real story is less dramatic — but probably more important.
For the first time in decades, the mortgage industry is moving away from reliance on a single credit-scoring model and toward genuine competition among models.
For some future homebuyers, that may ultimately mean their financial history gets looked at a little differently.
And when you're trying to turn “I'd like to own a home” into “When do I get the keys?”, a different look can matter.
DISCLAIMER: This article is provided for general informational and educational purposes only and is not intended as financial, credit, lending, legal, or mortgage advice. Credit-scoring models, lender requirements, loan programs, and underwriting standards may change and may vary by lender and borrower and state. Credit scores are only one factor considered in mortgage qualification. Buyers should consult directly with a qualified mortgage professional regarding their individual circumstances.
#RealEstate #HomeBuying #HomeBuyers #Mortgage #MortgageTips #CreditScore #FICO #VantageScore #VantageScore4 #FannieMae #FreddieMac #FirstTimeHomeBuyer #Homeownership #RealEstateEducation #KartalHomes #FindYourWayForward #WaypointProperties @WaypointProperties